Harvesting Losses Honestly
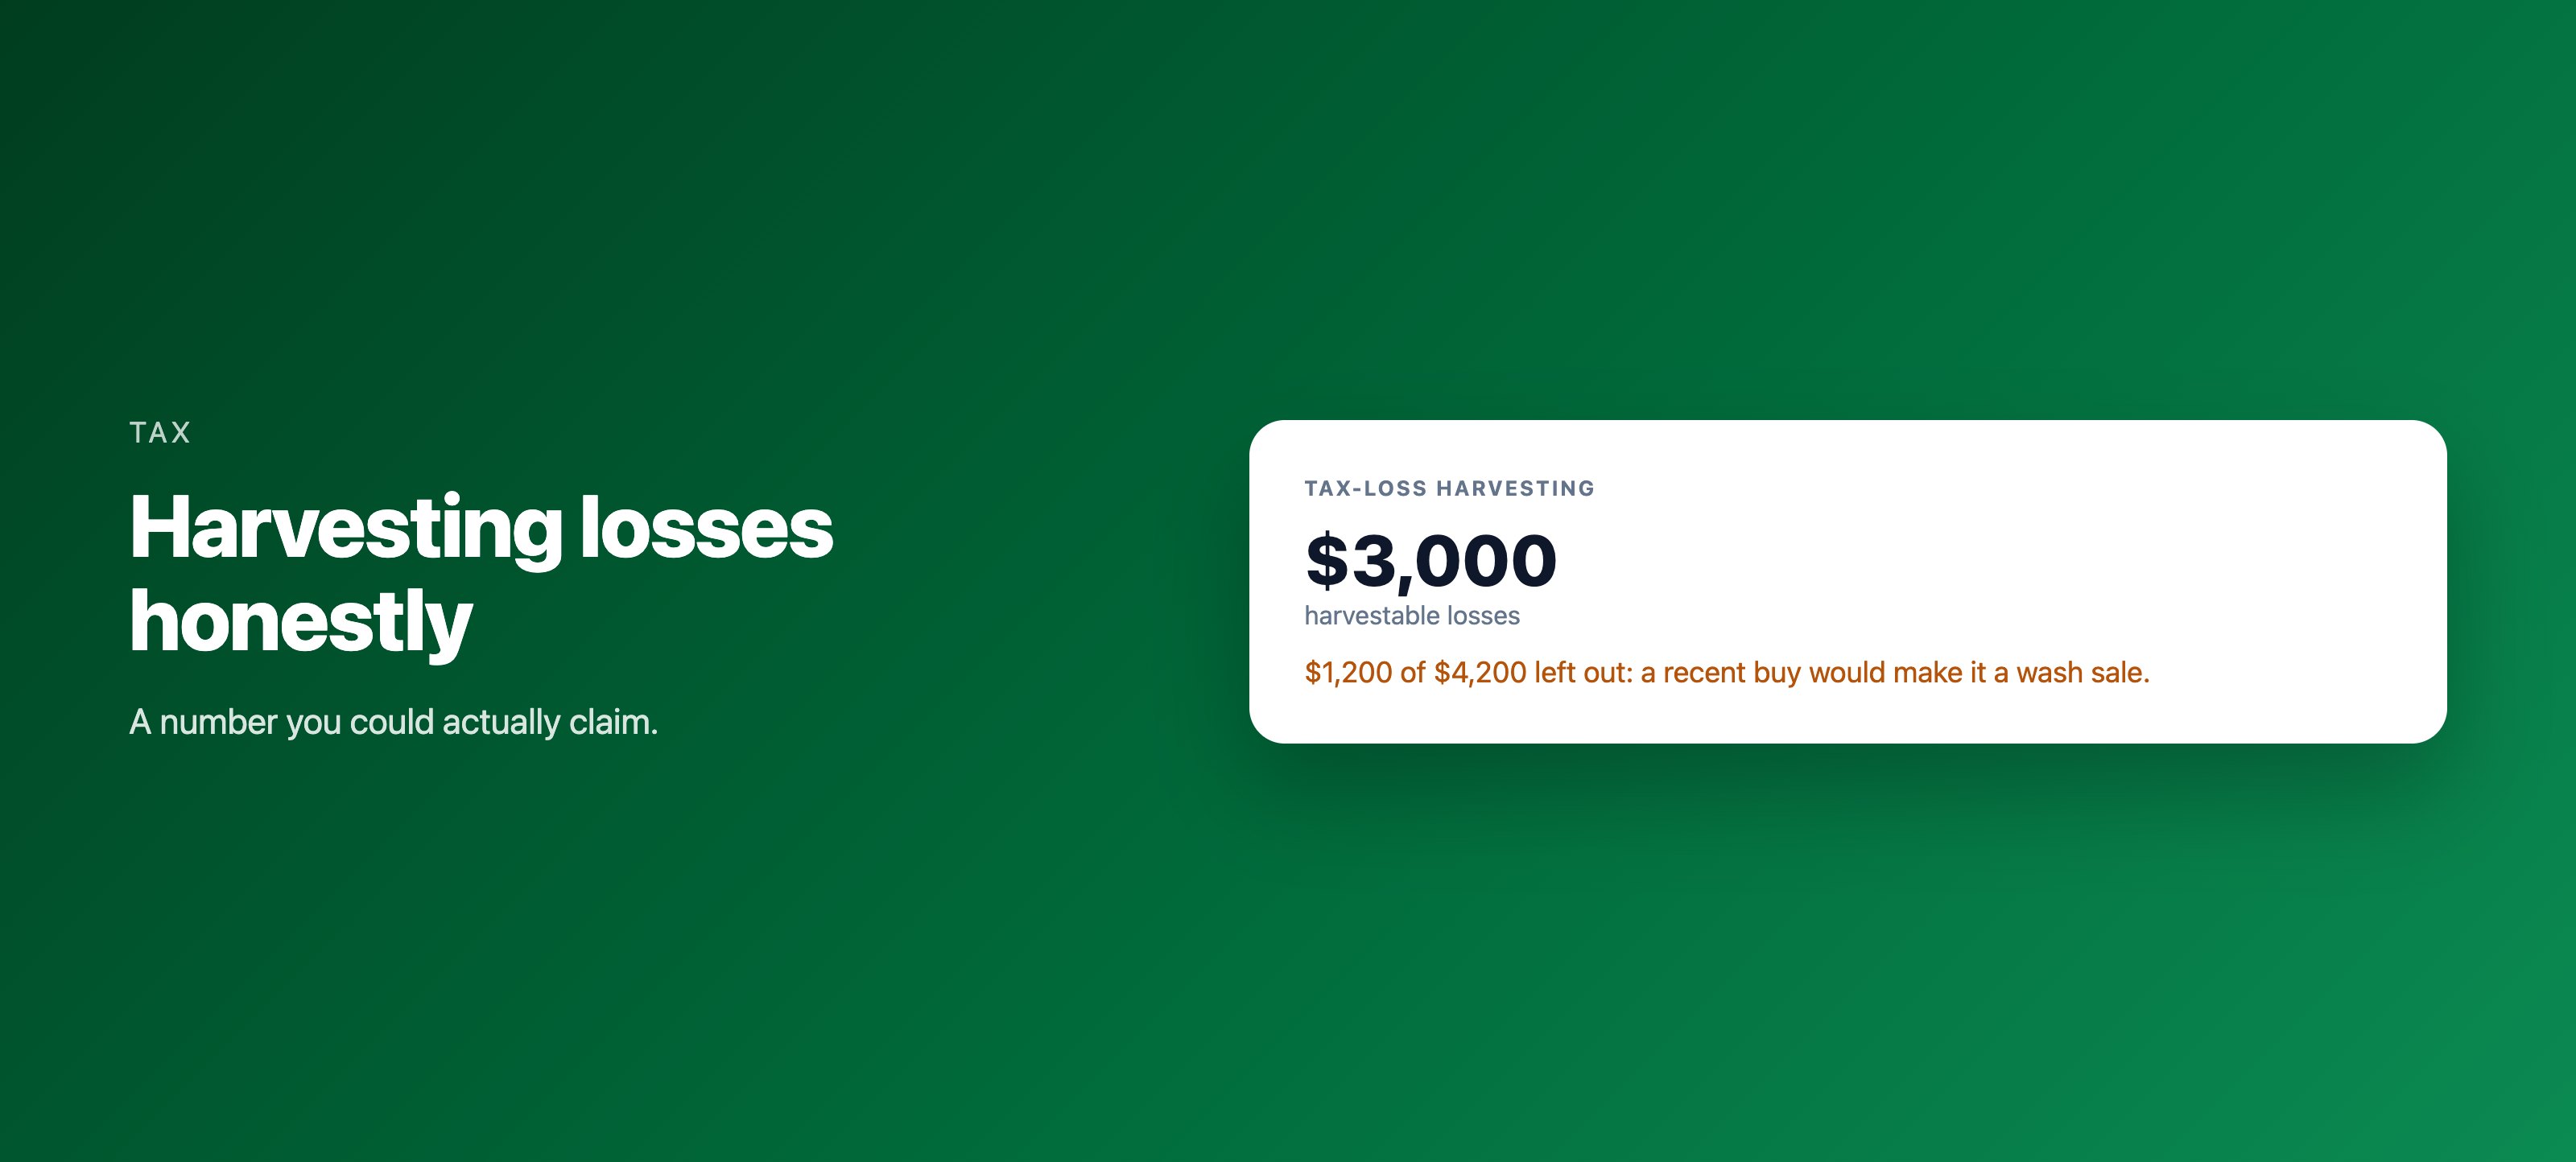
A tax-loss harvesting number is only useful if it is one you can actually claim. Ours now leaves out the part a recent purchase would disallow as a wash sale, and when a wash sale does happen, it shows where the disallowed loss went.
Tax-loss harvesting is simple to describe. You sell a holding that is worth less than you paid, the loss offsets gains elsewhere, and you pay less tax. The catch is a rule that most people meet only when their tax software flags it: if you buy the same security within 30 days before or after the sale, the loss is disallowed.
Until now our harvesting page showed a headline built from every losing lot. It flagged the lots with a recent purchase as a risk, but the headline still counted them in full. That made the number bigger than the one you could actually claim, and a bigger number is not a more useful one.
What changed in the headline
Shares you bought in the last 30 days that you would still hold after selling the losers are replacement shares. We match them to your losing lots oldest first, the way a sale of the whole holding would consume them, and leave that part of each loss out of the total.
- A recent purchase that is itself a losing lot you would sell is not a replacement: if it goes too, nothing replaces anything.
- Purchases in your other portfolios count, because the rule applies to you as a taxpayer, not to one account.
- A security bought under a different spelling of its symbol counts as the same security. More on that in our post about ticker spellings.
The page now shows two numbers where there used to be one: the losses you could harvest today, and the amount a recent purchase holds back. Each lot shows its own held-back part, so you can see which purchase is doing it.
See which of your own holdings show a loss you could look at.
Start freeWhere a disallowed loss goes
A wash sale does not make the loss disappear. It moves it. The disallowed amount is added to the cost basis of the replacement shares, and the holding period of the shares you sold is added to theirs. When you eventually sell the replacement shares, the higher basis gives the loss back.
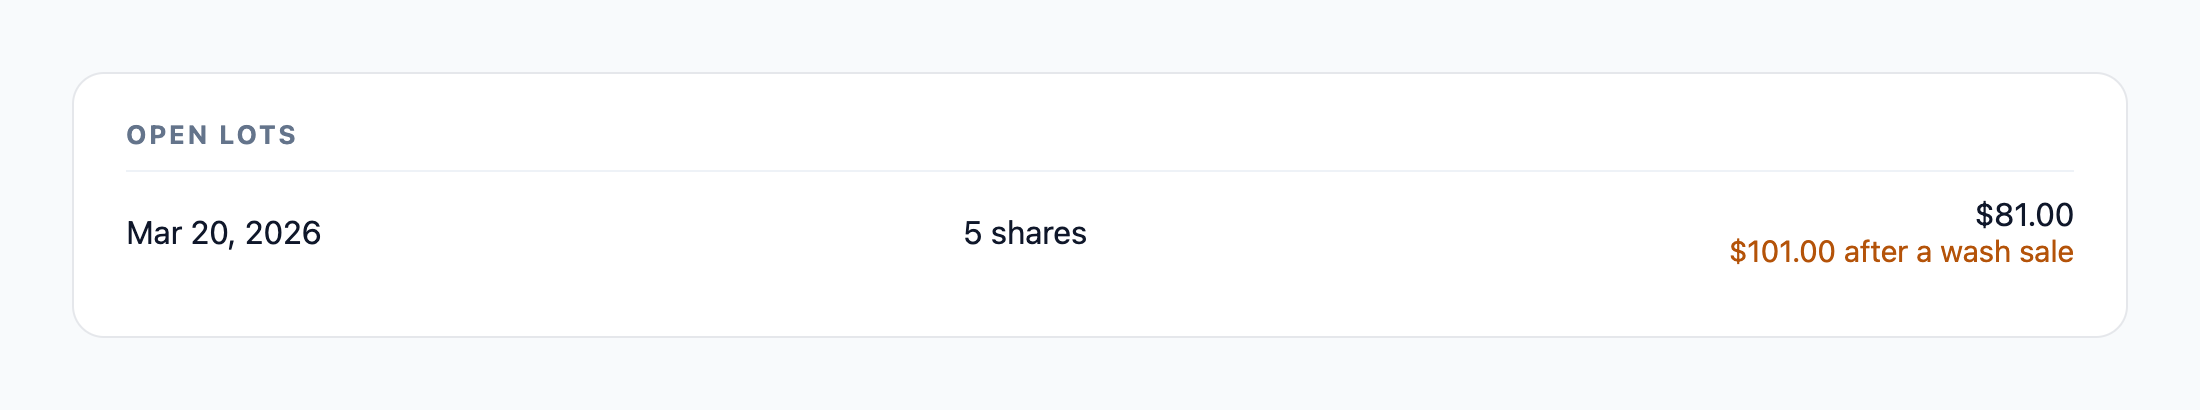
Your lots now show that roll. Next to the price you paid, a replacement lot shows its adjusted basis after the wash sale, and its holding period counts the days the sold shares were held. The recorded trade stays exactly as it happened; the adjusted figures sit beside it, labelled, so you can reconcile both against the forms your broker sends.
Why we did not rewrite the books
The adjustment is shown, not written into your ledger. Your ledger records what you traded, at the prices you traded, and it matches your broker's statements line for line. Tax forms apply the wash sale rule on top of that record, and so do we. Keeping the two apart means you can always see what happened and what the tax rule does to it, separately.
Frequently asked questions
What is a wash sale?
A wash sale is a sale of a security at a loss when the same security is bought within 30 days before or after the sale. The loss is disallowed for that year and added to the cost basis of the replacement shares.
Does Moneyta's harvesting figure include losses a wash sale would disallow?
No. The harvesting headline leaves out the part of each loss that shares bought in the last 30 days would disallow, and shows that held-back amount separately.
Does a purchase in another account count for the wash sale rule?
Yes. The rule applies per taxpayer, so Moneyta counts recent purchases of the same security in all of your portfolios.